

True Finance: Cash Advance
by JoinTrueDev
4.4
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.4
- Price
- Free
- Download
- 1.00M
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
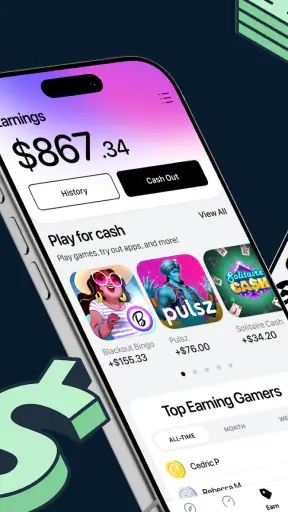
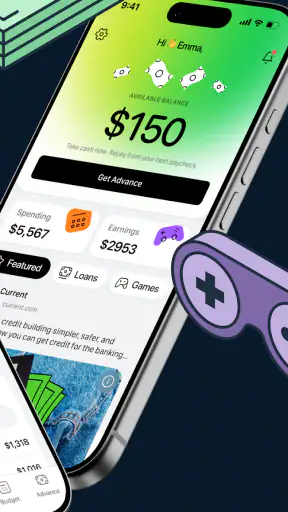
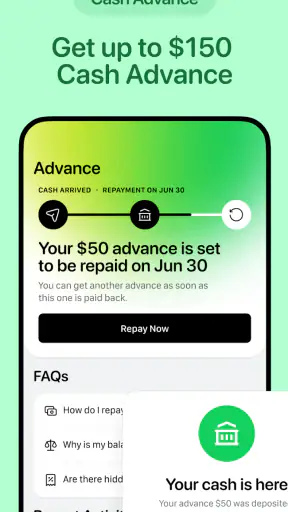
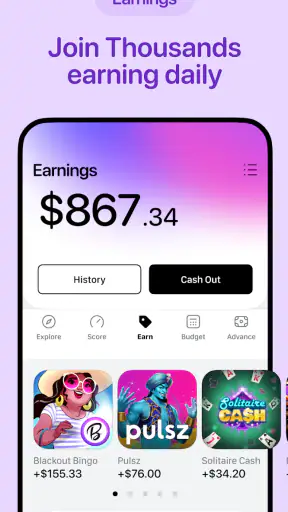
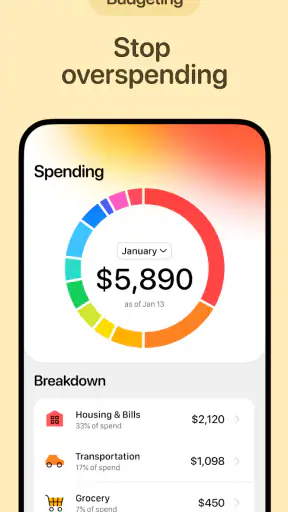
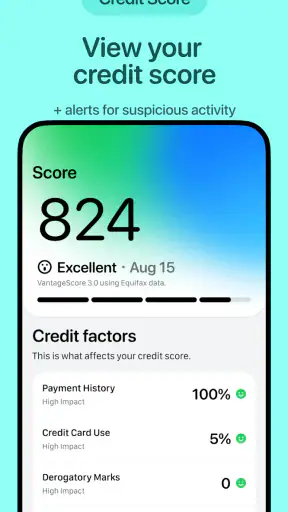
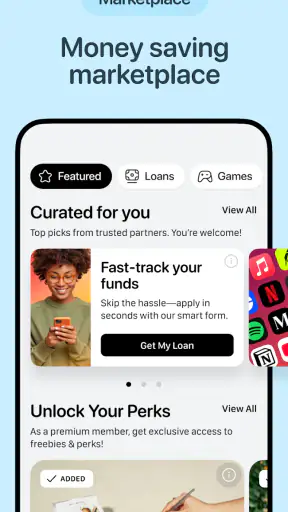
 Analysis by Getfullapps
When an unexpected bill lands between paydays, the appeal of a cash advance app is easy to understand. I looked at True Finance: Cash Advance as a practical finance tool rather than treating its promise of fast cash as a complete solution. The important question is not simply whether it can help in an emergency, but whether its process, eligibility expectations, and repayment demands fit the way you manage money.
True Finance: Cash Advance is a free finance app from JoinTrueDev, aimed at people looking for short-term access to money without relying on a conventional credit-check experience. It is available to an Everyone audience, runs on Android versions from 7.0 onward, and has reached over a million installs. Its current version is 10.6.0, while the app itself first appeared on December 21, 2022.
My overall view is cautiously positive. I can see why the app has attracted a 4.4 average from roughly 47 thousand ratings and about 4.2 thousand written reviews. It focuses on a very specific problem and keeps the basic idea understandable. At the same time, a cash advance should never be judged like a normal budgeting app. Speed matters, but so do repayment timing, total cost, eligibility, and what happens if the next paycheck is already committed.
How I would decide whether it fits
When I decide whether a short-term finance tool belongs in my routine, I start by asking what problem I expect it to solve and how often that problem actually occurs. I also consider whether I can keep the decision separate from the pressure of an urgent bill. That helps me judge the app on fit rather than on how appealing a quick option feels in the moment.
Start with the emergency, not the download
I would only consider this type of app after defining the exact gap I am trying to cover. A necessary prescription, a utility payment, or a small transportation problem is a different situation from shopping, entertainment, or trying to stretch an already unaffordable lifestyle. Writing down the amount needed and the date it must be paid makes the decision more concrete before I begin any application process.
The store summary presents the service around fast cash and no credit check. That is useful positioning, but it should not be interpreted as guaranteed approval or guaranteed money on demand. A person can still face eligibility checks, identity steps, account requirements, or other conditions during the process. I would read every screen carefully instead of tapping through simply because the need feels urgent.
Another decision point is repayment. The right question is not “Can I receive money today?” but “Can I repay it without creating a second emergency?” If the answer depends on skipping groceries, delaying another bill, or taking another advance, I would stop. A convenient short-term tool becomes risky when it turns into a repeating cycle.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
What I would inspect before accepting anything
Before confirming a request, I would look for the amount available, the amount that must be repaid, the expected repayment date, and any optional or required charges shown in the app. I would also check whether the timing matches my actual income rather than an optimistic estimate. A few days of difference can matter when a bank balance is already tight.
I would keep screenshots or notes of the final terms and the repayment schedule. This is not unnecessary caution. Cash advance decisions are often made under pressure, and people remember the amount received more easily than the full amount owed. Recording both figures gives me something clear to compare with my next pay cycle.
Because the app is free to install, the download itself does not tell me what a particular advance will cost. That distinction is important. “Free” describes access to the app, not automatically the financial terms of every transaction. I would never choose it based on the installation price alone.
A realistic everyday test
Imagine I need money to cover a car repair so I can get to work, and my paycheck arrives soon enough to repay the advance without cutting into rent or food. In that narrow case, True Finance: Cash Advance may be worth checking because it is designed around a short-term cash gap rather than long-term financial planning.
Now change the scenario: my account is already short because of rent, subscriptions, and another repayment. Getting a new advance might solve the repair today while making the following week worse. I would compare the app with a payment extension, a conversation with the bill provider, a trusted personal contact, or a lower-cost borrowing option before accepting new debt.
Who is likely to benefit
I think the app is most relevant to an adult who has a temporary timing problem, understands the repayment obligation, and wants to investigate an alternative to a traditional credit application. It may also appeal to someone whose credit history makes conventional options difficult to access, although “no credit check” should not be confused with “no financial responsibility.” The repayment still has to fit the user’s budget.
It is less suitable for someone seeking a long-term loan, debt consolidation, investment guidance, detailed expense tracking, or a complete personal-finance system. The app’s purpose is narrow. Choosing it for a job it was not designed to do would be like using a quick patch as a permanent repair.
Where the focused approach works well
I find a focused tool most useful when the need is specific and temporary, because a narrow purpose can make a stressful decision easier to examine. The next question is whether that usefulness continues after the immediate pressure has passed. I would look for a repeatable way to assess each need without treating the option as an automatic part of payday.
A simple path can matter under pressure
The biggest strength is focus. When I am dealing with an urgent expense, I do not necessarily want to build a full budget, categorize months of transactions, or compare a long list of lending products. An app centered on cash advances can reduce the mental distance between identifying a shortfall and exploring a possible solution.
That focus is also why the app feels different from ordinary finance apps. Budgeting tools are excellent for seeing patterns, but they do not directly address an immediate gap. Traditional lenders may offer broader products, yet their applications can feel heavier and may depend more visibly on credit history. True Finance sits in the space between those experiences: more targeted than a budget planner and potentially more accessible than a conventional credit route.
The no-credit-check positioning has a specific value
For people who have limited credit history or previous credit problems, the app’s central promise may be the reason to investigate it. A conventional score is not always a complete picture of someone’s current ability to repay. Removing that particular barrier can make an app feel more approachable when time is limited.
Still, I would treat this as an access feature, not a reason to borrow automatically. A service can be easier to apply for while remaining expensive or difficult to repay. The useful comparison is not only whether I can qualify, but whether the complete obligation is better than the alternatives available to me.
Three habits that make the experience safer
First, I would use a separate note on my phone to record the requested amount, expected repayment date, and final repayment amount before accepting. This turns a fast decision into something I can review calmly. It also helps me notice if the advance would overlap with another scheduled payment.
Second, I would make the repayment date part of my normal payday routine. I would check the balance before spending, rather than assuming the money left over is available. This small workflow is especially useful when several automatic payments arrive around the same time.
Third, I would treat a second request as a warning signal. If I need another advance before the first one is comfortably resolved, I would pause and review the underlying expense pattern. The app may be useful for an isolated disruption, but repeated reliance suggests that a different solution is needed.
What the public response tells me—and what it does not
The app’s scale and rating suggest that many people find the concept useful enough to keep using or recommend through their ratings. That gives me some confidence that it is not an obscure experiment with no user base. However, an average rating cannot tell me whether the exact terms, eligibility outcome, or repayment experience will match my situation.
I would read recent written feedback with a specific purpose: looking for comments about clarity, timing, customer support, and the difference between the amount requested and the amount repaid. I would not rely on a few enthusiastic or angry comments as proof of what will happen to everyone. Finance apps are particularly sensitive to individual circumstances.
Friction I would expect to manage
The first friction is emotional rather than technical: urgency makes people less careful. A fast interface can be helpful, but it can also encourage a rushed commitment. I would slow down at the final confirmation screen and review the obligation as if I were explaining it to a friend.
The second is that an advance does not remove the original financial problem; it moves money from a future date into the present. That can be exactly what I need for a short timing mismatch, but it is not a substitute for income, savings, or a sustainable debt plan.
The third is comparison. Since the app is specialized, I would still check whether a bill extension, employer option, bank product, credit-union service, or personal arrangement costs less and gives me more breathing room. The fastest route is not automatically the best route.
When another category may fit better
A product designed around one kind of financial need can be convenient, but convenience is not the same as a complete plan. I would choose a different category if my real goal were to understand recurring spending, borrow over a longer period, or arrange a payment without adding a separate obligation. Thinking through that distinction makes it easier to spot when the tool is solving the wrong problem.
Budgeting apps are better for recurring shortfalls
If I regularly run out of money before payday, I would choose a budgeting or expense-tracking app as the main tool. That category can help reveal whether the problem comes from subscription renewals, irregular bills, food spending, transport, or income timing. True Finance may cover one gap, but it will not by itself explain why the gaps keep appearing.
A practical combination can be useful: use a budget tool to understand the pattern, then consider a cash advance only for a genuinely temporary event. I would not use repeated advances as a replacement for the planning work that prevents them.
Traditional lenders may be better for larger or longer borrowing
For a larger purchase or a repayment period extending beyond the next income cycle, I would compare personal-loan, bank, and credit-union options. Those alternatives may involve more paperwork or stricter eligibility, but they can be more appropriate when the need is substantial. A short-term advance is a poor match for a long-term obligation.
Someone with strong credit should not assume that avoiding a credit check is automatically an advantage. If a bank or credit union can offer clearer terms and a lower overall cost, the more conventional route may be worth the extra application effort. The best choice depends on the complete repayment picture, not on the speed of the first screen.
Payment arrangements can beat borrowing
For a utility bill, medical invoice, rent issue, or service payment, I would contact the provider before borrowing. A short extension or installment arrangement may solve the timing problem without adding a separate financial obligation. This option is easy to overlook because it requires a conversation, but it can be cheaper than taking money from an advance service.
I would also consider whether the expense can be delayed, reduced, or paid in another way. That sounds obvious, yet it is often the most valuable comparison when the requested amount is small. Borrowing less is usually simpler than borrowing the full amount and hoping the next paycheck absorbs it.
Who should skip this app
I would skip True Finance: Cash Advance if I cannot identify a reliable repayment source, if my essential bills already exceed my income, or if I am considering it for discretionary spending. I would also avoid it if I am looking for credit-building, investment features, or a detailed financial dashboard. Those goals call for different categories of products.
People who are uncomfortable reviewing financial terms on a phone should be especially careful. The app may be convenient, but convenience does not replace understanding. If I cannot explain the repayment date and total obligation in plain language, I am not ready to accept the advance.
The cost of changing tools
Changing tools has a practical cost: I may have to rebuild habits, recheck upcoming obligations, and make sure a new process does not obscure the wider budget. I would avoid switching just because one route feels quicker; instead, I would compare the effort saved with the clarity and control I might lose. That trade-off is especially worth considering when money is already tight.
Moving from a normal finance app
If I am coming from a budgeting app, the change is not mainly about learning a new interface. It is about changing the decision I am making. A budget app is usually a planning and visibility tool; True Finance is centered on accessing money for a short-term need. I would keep my existing budgeting habit instead of abandoning it just because I installed a cash advance app.
The useful workflow is to check the budget first, calculate what the next paycheck must cover, and only then investigate an advance. That order prevents the cash request from becoming the starting point. It also makes it easier to see whether the advance genuinely solves a timing issue or merely delays a larger deficit.
Moving from a traditional lender
Someone used to a bank or credit union may find the focused approach less comprehensive. There may be fewer reasons to visit the app when I need a broader loan, savings product, credit-building plan, or ongoing financial relationship. In exchange, the appeal is a more direct path for the narrow cash-gap scenario.
I would compare the effort saved with the obligation created. A quicker application is valuable only if the terms are clear and repayment is realistic. If a traditional option takes longer but gives me a lower total cost or a more manageable schedule, switching to the faster route may be a false economy.
What to do after an advance
Once the immediate expense is handled, I would not simply delete the app and forget the experience. I would review why the emergency happened, whether the amount was accurate, and whether my next paycheck can cover the repayment without another compromise. That review is the difference between using a tool deliberately and letting it become part of a cycle.
I would also remove the app from my emergency-plan shortlist if the final terms were unclear or if the repayment timing did not work for my income schedule. A product can be well rated and still be wrong for me. Personal fit matters more than popularity when the decision affects a tight budget.
My recommendation
After weighing the categories, I would recommend True Finance: Cash Advance only as a narrowly defined emergency option. Its free access, focused purpose, broad availability, and no-credit-check positioning make it worth investigating for someone facing a temporary cash-timing problem. The app has a substantial user base, and its 4.4 average indicates generally favorable reception.
My recommendation comes with a firm condition: use it only when the repayment plan is already believable before the money is requested. Read the final terms, note the full obligation, and compare the result with a bill extension, a bank or credit-union option, a budgeting adjustment, or help from a trusted person. Never let the phrase “fast cash” replace a cost comparison.
For recurring shortages, I would choose budgeting support and address the income-versus-expenses problem. For larger borrowing, I would investigate traditional lending. For a small, isolated gap that can be repaid comfortably, this app may be a practical candidate. That is the boundary I would give a friend: True Finance: Cash Advance can be useful as a short bridge, but it should not become the road you depend on every payday.
Pros
- Simple interface makes requesting an advance easy to understand.
- May help cover urgent expenses before your next paycheck.
- Application process can be completed entirely from a mobile device.
- Repayment details are shown before accepting an advance.
- Useful budgeting tools may help users monitor upcoming cash needs.
Cons
- Eligibility and advance limits can vary significantly between users.
- Funding speed may depend on your bank and selected transfer method.
- Late repayment could lead to additional fees or financial stress.
- Requires access to personal and financial information during signup.
- Not a substitute for long-term budgeting or emergency savings.
FAQs for True Finance: Cash Advance
What is True Finance: Cash Advance, and how does it work?
True Finance: Cash Advance is a financial app designed to help eligible users review potential cash advance options and manage short-term money needs. After creating an account, you may be asked to provide personal, employment, income, and banking information. The app can then connect you with available offers or financial service providers. Approval, advance amounts, fees, and repayment terms vary by user and provider.
Is True Finance: Cash Advance a direct lender?
Not necessarily. True Finance: Cash Advance may operate as a connection service or marketplace rather than providing every advance directly. Depending on your profile and location, your request could be shared with third-party lenders or financial providers. Before accepting an offer, carefully check the provider’s identity, annual percentage rate, fees, repayment schedule, privacy policy, and any authorization for automatic withdrawals.
What information is required to use True Finance: Cash Advance?
Users should expect to provide information such as their name, contact details, date of birth, address, employment status, income, bank account details, and identity verification data. This information is commonly used to evaluate eligibility and match users with financial providers. Only submit details through the official app or website, review the privacy terms, and avoid entering sensitive information into unofficial copies.
How much money can I receive, and how quickly is it deposited?
The amount and delivery time depend on eligibility, your financial profile, the provider making the offer, and your bank’s processing schedule. The app does not guarantee approval, a specific advance amount, or instant funding for every user. Some providers may deposit funds quickly, while others can take longer. Review the final agreement for fees, repayment dates, and funding conditions.
What should I check before accepting a cash advance through the app?
Before accepting any offer, compare the total repayment amount with the amount you receive, not just the advertised fee. Check the APR, origination or service charges, late-payment penalties, renewal terms, repayment date, and whether automatic bank withdrawals are required. Make sure the payment fits your budget, read the complete agreement, and remember that short-term advances can become expensive if repeatedly renewed.

True Finance: Cash Advance
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via contact@jointrue.com, visit https://jointrue.com, or review their https://jointrue.com/privacy-policy.










